How to Build an Emergency Fund in India (2026 Guide)
By FinanceBlogg Editorial Team
Published 8 min read
Editorially reviewed by FinanceBlogg Editorial Team on . How we review articles
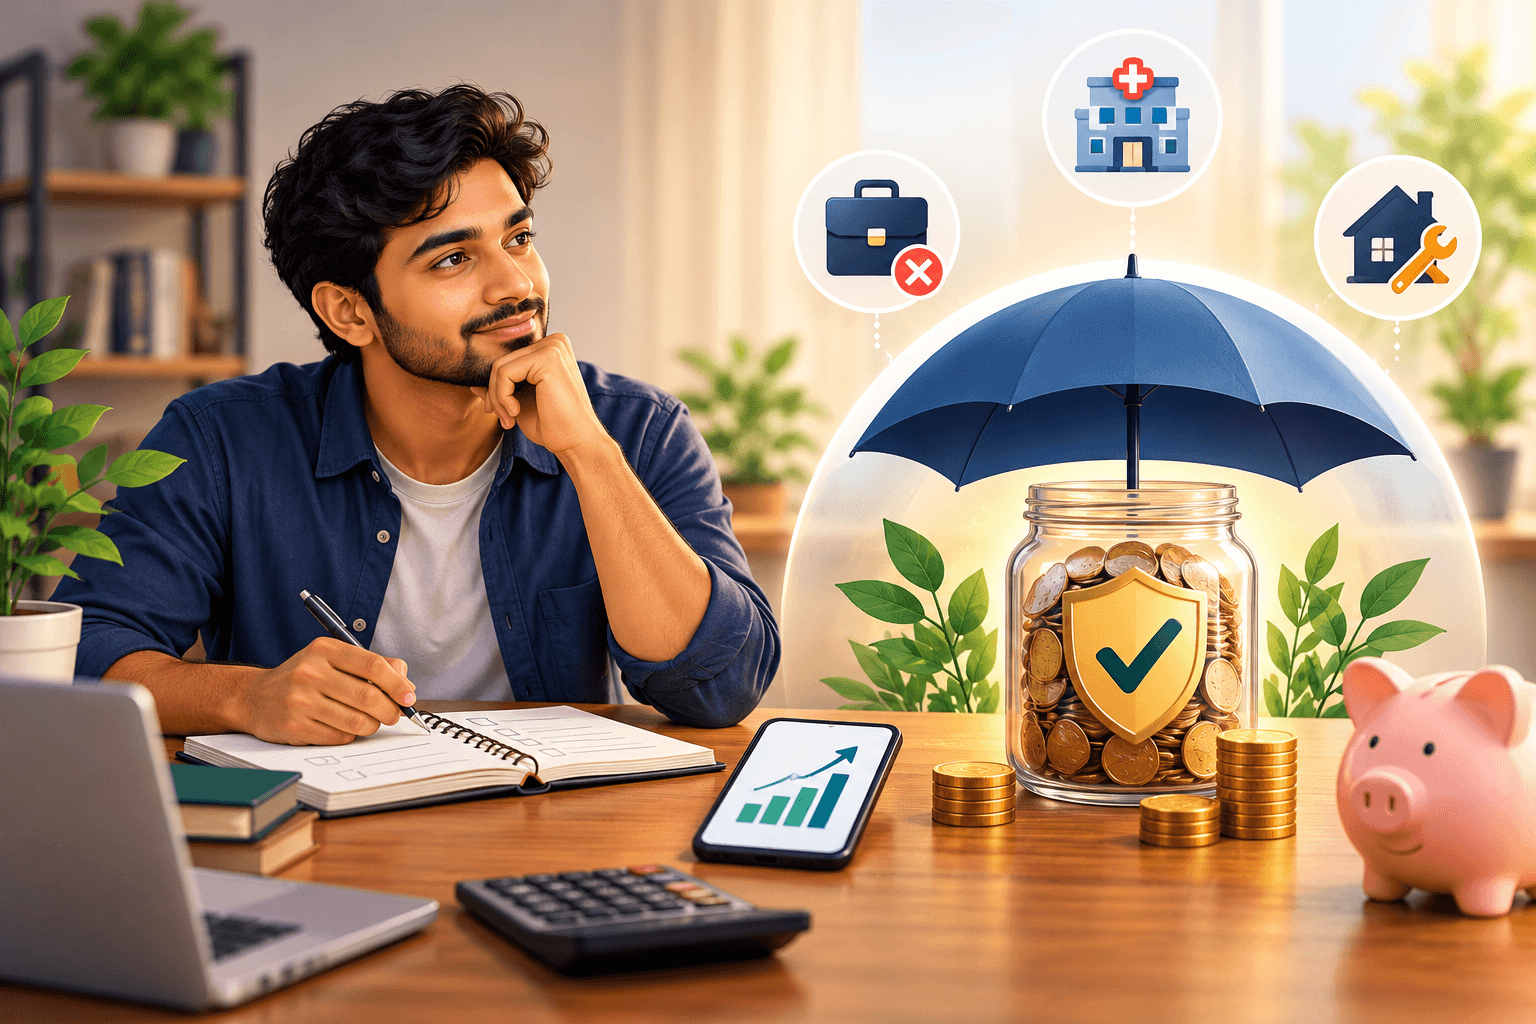
How to Build an Emergency Fund in India: A Practical Step-by-Step Guide
Unexpected expenses can disrupt even a carefully planned budget. A medical emergency, sudden job loss, urgent home repair or temporary loss of business income can put considerable pressure on your finances.
This is why building an emergency fund is one of the most important steps towards financial stability.
An emergency fund is money kept aside specifically for unexpected financial situations. It helps you manage difficult circumstances without depending heavily on credit cards, personal loans or withdrawing long-term investments.
In this guide, we explain how to build an emergency fund in India, how much money you should save, where to keep it and how to create a savings plan that works with your monthly income.
What Is an Emergency Fund?
An emergency fund is a dedicated savings reserve that you can access when unexpected financial expenses arise.
Unlike regular savings for holidays, shopping or purchasing a vehicle, emergency savings are meant for situations that cannot easily be postponed.
Some common examples include:
- Unexpected medical expenses.
- Sudden unemployment or salary reduction.
- Emergency home or vehicle repairs.
- Temporary business income loss.
- Urgent family responsibilities.
- Essential travel due to unforeseen circumstances.
The main purpose of an emergency fund is financial protection, not generating high investment returns.
According to the National Institute of Securities Markets (NISM), emergency savings should prioritise safety and liquidity so that money is available when required.
How Much Emergency Fund Should You Have in India?
A common starting point is to save an amount equivalent to three to six months of essential living expenses.
However, the right amount depends on your employment stability, family responsibilities, income sources and financial commitments.
For example:
- Salaried employees with stable income may begin with three to six months of essential expenses.
- Self-employed individuals may prefer a larger reserve.
- Freelancers and business owners with irregular income may consider six to twelve months of essential expenses.
The goal is to create a financial cushion that gives you enough time to manage an unexpected situation.
Emergency Fund Calculation Example
Suppose your monthly essential expenses are:
| Expense | Monthly amount |
|---|---|
| House rent | ₹10,000 |
| Groceries | ₹6,000 |
| Electricity and utilities | ₹2,000 |
| Transportation | ₹3,000 |
| Medical expenses | ₹2,000 |
| Loan EMI | ₹5,000 |
| Other essential expenses | ₹2,000 |
| Total | ₹30,000 |
Your emergency fund target would be:
| Coverage period | Savings target |
|---|---|
| 3 months | ₹90,000 |
| 6 months | ₹1,80,000 |
| 9 months | ₹2,70,000 |
| 12 months | ₹3,60,000 |
If your essential monthly expenses are ₹30,000, a six-month emergency fund would be ₹1,80,000.
Remember to calculate essential expenses rather than your entire monthly salary.
7 Practical Steps to Build an Emergency Fund
1. Calculate Your Essential Monthly Expenses
Start by understanding how much money you actually need to maintain your household every month.
Review your recent bank statements and identify necessary expenses such as:
- Rent or home loan EMI.
- Groceries and household supplies.
- Electricity, water and internet.
- Transportation.
- Insurance premiums.
- Essential medical expenses.
- Minimum required loan repayments.
Separate these expenses from discretionary spending such as entertainment, shopping and dining out.
This gives you a realistic emergency savings target.
2. Set a Realistic Savings Target
Avoid trying to save a very large amount immediately.
Start with a smaller milestone and increase your target gradually.
For example, you can divide your savings journey into three stages:
- First milestone: ₹10,000.
- Second milestone: One month of essential expenses.
- Final milestone: Three to six months of essential expenses.
Smaller milestones make your financial goals easier to track and maintain.
3. Create a Separate Savings Account
One effective way to manage emergency savings is to keep them separate from your everyday spending money.
Consider using a separate bank savings account for this purpose.
This approach helps you:
- Track your emergency savings easily.
- Avoid accidental spending.
- Access money when required.
- Maintain better financial discipline.
Compare account fees, minimum balance requirements, withdrawal conditions and access options before selecting an account.
4. Automate Your Monthly Savings
Saving becomes easier when you make it a regular financial habit.
Set up an automatic transfer from your primary bank account to your emergency savings account after receiving your salary or business income.
For example, if you save ₹3,000 every month:
| Saving period | Total savings |
|---|---|
| 3 months | ₹9,000 |
| 6 months | ₹18,000 |
| 12 months | ₹36,000 |
| 24 months | ₹72,000 |
| 36 months | ₹1,08,000 |
These figures exclude any interest earned.
Even a modest monthly contribution can gradually create a meaningful financial reserve.
5. Reduce Unnecessary Expenses
Review your monthly spending to identify expenses that can be reduced without affecting your essential needs.
Consider these changes:
- Cancel subscriptions you rarely use.
- Reduce unnecessary online purchases.
- Plan grocery shopping in advance.
- Compare service and mobile plans.
- Limit impulse purchases.
- Review recurring charges on your bank and card statements.
You don't need to eliminate every enjoyable expense. The objective is to create a sustainable balance between spending and saving.
6. Use Extra Income to Increase Savings
Whenever you receive additional income, consider directing a portion towards your emergency fund.
Examples include:
- Annual bonuses.
- Freelance payments.
- Business profits.
- Tax refunds.
- Additional income from side projects.
For example, if you receive an unexpected ₹10,000 payment, you could allocate part of it to emergency savings instead of increasing your regular spending.
This can help you reach your savings target faster.
7. Review Your Emergency Fund Regularly
Your financial requirements can change over time.
A new home loan, marriage, children, increased rent or changing family responsibilities may increase your essential expenses.
Review your emergency fund at least once or twice a year.
If your monthly essential expenses increase, adjust your savings target accordingly.
Where Should You Keep Your Emergency Fund in India?
An emergency fund should be easy to access and relatively safe.
Different financial products offer different levels of liquidity and risk.
Here are some commonly considered options:
| Financial option | Main consideration |
|---|---|
| Bank savings account | Easy access to money |
| Sweep-in fixed deposit | May provide better interest with withdrawal flexibility, subject to terms |
| Short-term fixed deposit | Check premature withdrawal rules |
| Liquid mutual funds | Market-linked; returns and capital are not guaranteed |
You can consider keeping a portion in a savings account for immediate expenses and the remaining amount in suitable liquid savings arrangements.
Do not put your entire emergency fund into stocks, equity mutual funds, cryptocurrency or other volatile investments.
The purpose is to have money available when you need it, not to maximise investment returns.
Common Emergency Fund Mistakes to Avoid
Building an emergency fund is important, but managing it correctly is equally important.
Avoid these common mistakes:
1. Investing emergency savings in risky assets
Money required for emergencies should not depend on favourable market conditions.
2. Using emergency savings for shopping
A holiday, new smartphone or entertainment purchase is generally not an emergency.
3. Saving without a specific target
Set a clear savings goal based on essential monthly expenses.
4. Ignoring inflation and rising expenses
Your financial requirements may increase over time. Review your target regularly.
5. Delaying savings until your income increases
You can begin with a small monthly contribution and increase it as your financial position improves.
6. Depending entirely on credit cards
Credit cards can provide temporary payment flexibility, but they are not a replacement for an emergency fund. Outstanding balances can create additional financial pressure.
Emergency Fund vs Regular Savings: What's the Difference?
These two types of savings have different purposes.
| Feature | Emergency fund | Regular savings |
|---|---|---|
| Main purpose | Unexpected expenses | Planned purchases and goals |
| Usage | Financial emergencies | Holidays, shopping, education |
| Access | When an emergency occurs | According to your goals |
| Savings target | Usually 3–6 months or more of essential expenses | Depends on your goal |
| Priority | Financial protection | Future planned expenses |
Maintaining separate savings for different purposes makes financial planning easier.
Frequently Asked Questions (FAQs)
1. How much emergency fund should I have in India?
A common starting target is three to six months of essential living expenses. People with irregular income or additional family responsibilities may consider six to twelve months.
2. Can I build an emergency fund with ₹1,000 per month?
Yes. Saving ₹1,000 every month gives you ₹12,000 after one year, excluding interest. Start with an affordable amount and increase your contribution whenever possible.
3. Is a savings account good for an emergency fund?
A bank savings account can be useful because it generally provides convenient access to money. Compare account conditions, charges and applicable deposit protection before choosing a bank.
4. Should I invest my emergency fund in mutual funds?
An emergency fund should prioritise safety and liquidity. Certain liquid mutual funds may be considered for a portion of the reserve, but they are market-linked and do not guarantee capital or returns.
5. Should I pay off debt or build an emergency fund first?
Consider building a small emergency reserve while prioritising high-interest debt repayment. This can reduce the risk of taking on additional expensive debt when unexpected expenses arise.
6. When should I use my emergency fund?
Use it for genuine unexpected financial requirements, such as medical emergencies, sudden income loss or urgent essential repairs. Rebuild the fund after using it.
Final Thoughts
An emergency fund is not just another savings goal. It is an important part of a healthy financial plan.
You don't need a high salary or a large initial deposit to get started. Begin by calculating your essential expenses, set a realistic target and save consistently every month.
Over time, your emergency savings can provide greater financial confidence and help you handle unexpected situations without disrupting your long-term financial goals.
Start small, stay consistent and make financial security a priority.
Disclaimer: This article is for educational and informational purposes only. It should not be considered personalised financial, investment, tax or legal advice.
References
- Securities and Exchange Board of India (SEBI): Financial goals and budgeting.
- National Institute of Securities Markets (NISM): Saving for emergencies.
About the author
FinanceBlogg Editorial Team
Editorial Team
The FinanceBlogg editorial team researches and writes educational explainers on personal finance in India. Articles are based on official sources such as the Reserve Bank of India, SEBI, IRDAI and the Income Tax Department, and are updated when rules change.
View profile and articlesSpotted an error? Read our corrections policy and tell us.
Related articles
How to Choose the Right Savings Account in India: Fees, Minimum Balance and Hidden Charges
Learn how to choose the right savings account in India by comparing minimum balance rules, banking fees, ATM charges, digital services and deposit safety.
· 7 min read
How to Set Financial Goals in India
Turn vague money wishes into dated rupee amounts, with Indian examples for EMIs, school fees, festivals, emergency savings and retirement.
· 6 min read
CTC vs Take-Home Salary in India
How CTC differs from take-home salary in India: typical deductions, why in-hand is lower, and how to budget from the amount that actually arrives.
· 5 min read