How to Prioritise Financial Goals on One Salary in India
By FinanceBlogg Editorial Team
Published 9 min read
Editorially reviewed by FinanceBlogg Editorial Team on . How we review articles
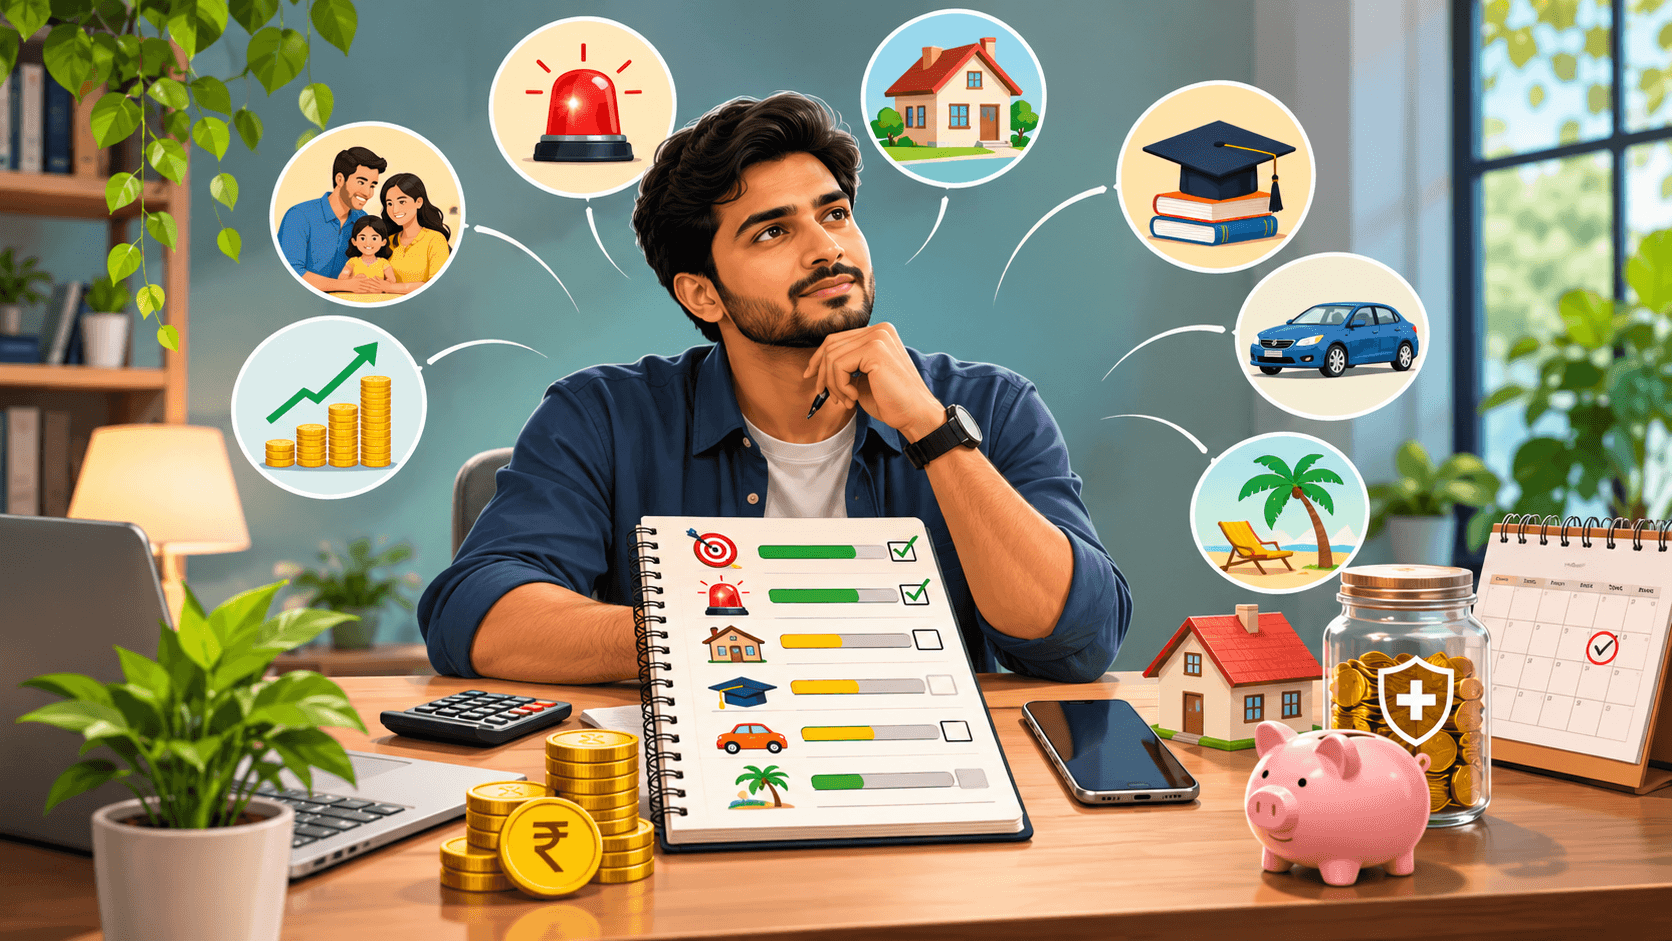
How to Prioritise Multiple Financial Goals on One Salary in India
Managing money becomes challenging when your salary has to support several financial goals at the same time. You may want to build an emergency fund, save for a house, pay off loans, support your children's education and prepare for retirement. However, trying to achieve every goal simultaneously without a proper plan can leave you financially stressed.
The good news is that you do not need a very high salary to start financial planning. What matters is understanding your priorities, setting realistic targets and allocating your money wisely.
In this guide, we explain how to prioritise multiple financial goals on one salary in India, with practical examples and a simple monthly savings framework.
Why Is It Difficult to Manage Multiple Financial Goals on One Salary?
Many salaried individuals receive a fixed monthly income, but their expenses and financial responsibilities keep changing.
For example, a person earning ₹50,000 per month may need to manage:
- Monthly household expenses
- Rent or home loan EMI
- Electricity, groceries and transportation
- Children's school fees
- Medical expenses
- Emergency savings
- Retirement planning
- Family functions and travel
When all these expenses compete for the same income, long-term savings often become the first thing people postpone.
Another common mistake is trying to save equal amounts for every goal without considering urgency, importance or the time available.
A better approach is to organise financial goals according to their priority and timeline.
1. List All Your Financial Goals
The first step is to understand exactly what you want to achieve financially.
Instead of keeping your goals in your mind, write them down in one place.
Some common financial goals for Indian households include:
Short-term goals (within 1–3 years)
- Building an emergency fund
- Paying off expensive credit card debt
- Saving for insurance premiums
- Planning a family vacation
- Purchasing essential household items
Medium-term goals (3–7 years)
- Saving for a vehicle
- Preparing for children's education
- Making a house down payment
- Starting a business
- Planning major family expenses
Long-term goals (more than 7 years)
- Retirement planning
- Purchasing a house
- Children's higher education
- Building long-term wealth
- Achieving financial independence
These timelines are planning categories, not fixed rules. Adjust them according to your actual deadlines.
2. Prioritise Financial Security Before Lifestyle Goals
Not every financial goal deserves equal priority.
For example, building an emergency fund is generally more important than saving for an expensive holiday.
A practical priority order is:
- Essential household expenses and minimum loan repayments.
- Emergency savings and adequate insurance protection.
- Repayment of high-interest debt.
- Important upcoming family and education expenses.
- Long-term retirement and wealth-building goals.
- Lifestyle goals such as holidays and luxury purchases.
The exact order may change depending on your circumstances. For example, a high-interest credit card balance may need urgent attention, while a family member's upcoming education expense may have a fixed deadline.
The important thing is to avoid sacrificing basic financial security for non-essential purchases.
3. Calculate How Much Money You Can Actually Save
Before allocating money to different goals, calculate your monthly surplus.
Use this simple formula:
Monthly Savings Capacity = Monthly Take-Home Income − Monthly Expenses − Required Debt Payments
Consider this example:
Suppose your monthly take-home salary is ₹50,000.
| Particulars | Monthly amount |
|---|---|
| Take-home salary | ₹50,000 |
| Household expenses | ₹22,000 |
| Rent | ₹8,000 |
| Loan EMI | ₹5,000 |
| Transportation and other expenses | ₹3,000 |
| Total expenses | ₹38,000 |
| Available monthly surplus | ₹12,000 |
In this example, ₹12,000 is the amount available for additional savings and financial goals.
This calculation helps you avoid making unrealistic savings commitments.
4. Divide Your Savings Between Different Financial Goals
Once you know your monthly savings capacity, allocate it according to your priorities.
For example, someone with ₹12,000 available every month might use this illustrative allocation:
| Financial goal | Monthly allocation |
|---|---|
| Emergency fund | ₹4,000 |
| Children's education | ₹2,500 |
| Retirement savings | ₹2,500 |
| Upcoming family expenses | ₹1,500 |
| Personal goal or travel | ₹1,500 |
| Total | ₹12,000 |
These amounts are only an example, not a recommended allocation for every household.
If you have no emergency savings, you may temporarily direct more money towards building your financial safety net. If you have expensive outstanding debt, you may need to prioritise repayment instead.
The key is to assign a purpose to every rupee rather than saving whatever remains at the end of the month.
5. Set a Target Amount and Deadline for Every Goal
A financial goal becomes easier to manage when you know how much money you need and when you need it.
For example:
| Goal | Target amount | Time available |
|---|---|---|
| Emergency fund | ₹1,50,000 | 24 months |
| Vehicle down payment | ₹1,20,000 | 36 months |
| Education savings | ₹2,00,000 | 60 months |
| Holiday | ₹60,000 | 12 months |
You can estimate the monthly savings required using this simple formula:
Monthly Savings Required = (Target Amount − Existing Savings) ÷ Remaining Months
For example, if you want to save ₹60,000 for a holiday in 12 months and already have ₹12,000 saved:
(₹60,000 − ₹12,000) ÷ 12 = ₹4,000 per month.
This calculation assumes no investment returns or interest.
If the required monthly contribution is too high, consider increasing the deadline, reducing the target or postponing a less important goal.
6. Build an Emergency Fund Before Taking Bigger Financial Risks
An emergency fund protects your financial plan when unexpected expenses arise.
Situations such as job loss, medical emergencies, urgent home repairs or temporary business income problems can disturb your monthly budget.
A commonly used starting target is three to six months of essential living expenses. People with unstable income, dependants or higher financial responsibilities may need a larger reserve.
For example, if your essential monthly expenses are ₹30,000:
- Three months of expenses: ₹90,000
- Six months of expenses: ₹1,80,000
You do not need to build the entire amount immediately. Start with a manageable monthly contribution and increase it when your income improves.
Keep emergency savings accessible and separate from money intended for long-term investments.
7. Avoid Taking on Too Many Financial Goals at Once
One of the biggest financial planning mistakes is trying to achieve everything simultaneously.
For example, a household may try to purchase a new car, save for a house, invest for retirement and plan an expensive holiday within the same year.
If the available income is limited, this approach may create unnecessary financial pressure.
Instead, divide your goals into three groups:
Must achieve: Essential goals such as emergency savings, debt repayment and important family responsibilities.
Should achieve: Important goals such as education savings, home ownership and retirement preparation.
Can wait: Flexible goals such as luxury purchases, expensive holidays or upgrading household electronics.
This approach does not mean abandoning your dreams. It simply means achieving them in a financially sensible order.
8. Increase Your Savings When Your Income Increases
Whenever you receive a salary increment, bonus or additional income, avoid increasing all your expenses immediately.
Consider directing a portion of the additional income towards:
- Completing your emergency fund.
- Increasing retirement contributions.
- Repaying outstanding debt.
- Saving for upcoming family responsibilities.
- Building funds for important long-term goals.
Even a modest increase in monthly savings can improve your progress over time.
For example, increasing your monthly savings from ₹5,000 to ₹6,000 means an additional ₹12,000 saved over one year, before considering any interest or returns.
9. Review Your Financial Goals Every Three Months
Financial planning is not something you do once and forget.
Your income, expenses and family responsibilities may change throughout the year.
Review your financial plan every three months and ask yourself:
- Am I saving the planned amount?
- Have my household expenses increased?
- Is any financial goal approaching its deadline?
- Have I taken on additional debt?
- Do I need to change my monthly savings allocation?
- Is my emergency fund sufficient for my current responsibilities?
If your financial situation changes, adjust your allocations rather than abandoning the entire plan.
Common Financial Planning Mistakes to Avoid
Here are some mistakes that can make it harder to achieve multiple financial goals:
1. Saving without a clear target: Saving money without knowing its purpose can make it difficult to measure progress.
2. Ignoring inflation: The cost of education, housing, healthcare and other expenses may increase over time. Review your future targets periodically.
3. Using emergency savings for shopping: Emergency funds should be reserved for genuine unexpected financial needs.
4. Taking unnecessary loans: Borrowing for lifestyle purchases can reduce the amount available for important goals.
5. Delaying retirement planning: Starting later may require larger monthly contributions to reach the same target.
6. Following unrealistic savings percentages: Your savings plan should reflect your actual income, essential expenses and responsibilities.
Frequently Asked Questions (FAQs)
1. How can I manage multiple financial goals on one salary in India?
Start by calculating your take-home income and essential expenses. Build an emergency fund, prioritise expensive debt and allocate the remaining savings towards important short-term, medium-term and long-term goals.
2. How much of my salary should I save every month?
There is no single savings percentage suitable for everyone. Your savings capacity depends on income, household expenses, debts and financial responsibilities. Start with an affordable amount and increase it gradually.
3. Which financial goal should I prioritise first?
Essential expenses, minimum debt repayments, emergency savings and adequate insurance protection are important starting priorities. After addressing immediate financial risks, focus on upcoming family responsibilities and long-term goals.
4. Should I save for retirement or my children's education first?
Both can be important. However, retirement has fewer alternative funding options because you cannot usually borrow your way through retirement. Consider balancing retirement contributions with education deadlines and your family's current financial needs.
5. How can I save money with a low monthly salary?
Track your expenses, distinguish needs from wants, avoid unnecessary borrowing and begin with small, consistent savings contributions. Increase your savings whenever your income improves.
6. Should I invest money for every financial goal?
Not necessarily. The appropriate place for money depends on when you need it, how much risk you can accept and whether you need immediate access. Short-term goals generally require greater attention to capital preservation and liquidity than long-term goals.
Final Thoughts
Managing multiple financial goals on one salary is possible when you have a clear plan and realistic expectations.
You do not need to achieve every financial goal at the same time. Start by understanding your income, protecting yourself against unexpected expenses and deciding which goals matter most.
Set specific targets, make regular contributions and review your progress every few months.
Remember, successful financial planning is not about earning the highest salary. It is about making thoughtful decisions with the money you already have.
Disclaimer: This article is intended for educational and informational purposes only. It does not constitute personalised financial, investment, tax or legal advice. Consider your individual circumstances and consult a qualified professional before making financial decisions.
References and Further Reading
- SEBI Investor – Financial Goals and Budgeting (opens in a new tab)
- SEBI Investor – Management of Income and Expenses (opens in a new tab)
- SEBI Investor – Why Save? (opens in a new tab)
- RBI – Financial Awareness and Management Education (opens in a new tab)
About the author
FinanceBlogg Editorial Team
Editorial Team
The FinanceBlogg editorial team researches and writes educational explainers on personal finance in India. Articles are based on official sources such as the Reserve Bank of India, SEBI, IRDAI and the Income Tax Department, and are updated when rules change.
View profile and articlesSpotted an error? Read our corrections policy and tell us.
Related articles
How to Build an Emergency Fund in India (2026 Guide)
Learn how to build an emergency fund in India, calculate your savings target, choose where to keep it and protect yourself from unexpected expenses.
· 8 min read
How to Choose the Right Savings Account in India: Fees, Minimum Balance and Hidden Charges
Learn how to choose the right savings account in India by comparing minimum balance rules, banking fees, ATM charges, digital services and deposit safety.
· 7 min read
How to Set Financial Goals in India
Turn vague money wishes into dated rupee amounts, with Indian examples for EMIs, school fees, festivals, emergency savings and retirement.
· 6 min read