Sinking Funds in India: How to Save for Annual Expenses Without Taking a Loan
By FinanceBlogg Editorial Team
Published 9 min read
Editorially reviewed by FinanceBlogg Editorial Team on . How we review articles
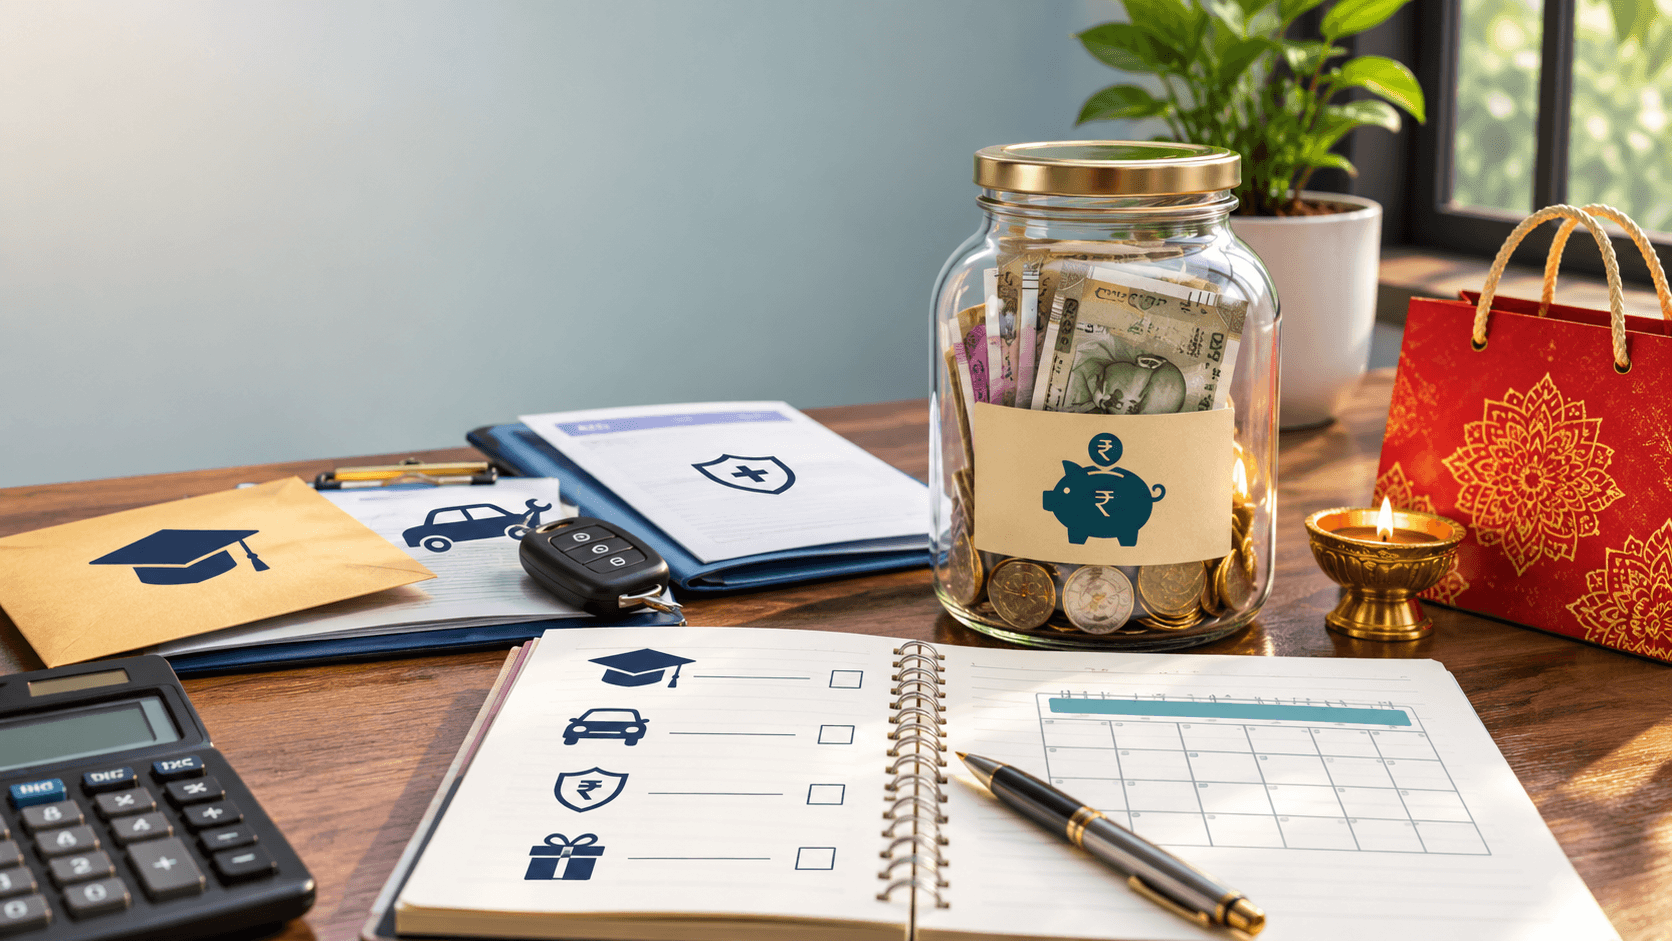
Sinking Funds in India: How to Save for Annual Expenses Without Taking a Loan
Category: Saving Money
Reading time: 8–10 minutes
Published by: FinanceBlogg Editorial Team
Have you ever received a school fee reminder, an annual insurance renewal notice or a vehicle maintenance bill and wondered where you would arrange the money?
These expenses are not unexpected. They happen every year, but many households forget to include them in their monthly budget.
This is where a sinking fund can help.
A sinking fund is a simple savings method in which you set aside a small amount of money regularly for a specific future expense. Instead of arranging a large amount at the last moment, you gradually build the required savings over several months.
In this guide, you will learn what a sinking fund is, how to create one in India, how much to save every month and how to use this method to manage annual household expenses without unnecessary borrowing.
What Is a Sinking Fund?
A sinking fund is money saved gradually for a planned expense that you expect to pay in the future.
For example, suppose your annual vehicle insurance premium is ₹12,000. Instead of arranging ₹12,000 when the renewal date arrives, you can save ₹1,000 every month.
After 12 months, you will have the required amount ready.
The same method can be used for:
- School and college fees
- Health and vehicle insurance premiums
- Festival celebrations
- Vehicle servicing
- Home repairs
- Annual subscriptions
- Property-related expenses
- Family functions and travel
The main purpose is to make large expenses easier to manage by spreading them across smaller monthly contributions.
Why Do Indian Households Need Sinking Funds?
Many families prepare a monthly budget but forget about expenses that occur only once or twice a year.
For example, a household might comfortably manage its monthly rent, groceries, electricity bills and transportation costs. However, when several annual expenses arrive together, the family may need to use a credit card, personal loan or emergency savings.
This creates unnecessary financial pressure.
A sinking fund helps solve this problem by preparing for known expenses in advance.
Here are some common situations:
1. School fees: Annual or term-based school payments can require a significant amount of money.
2. Insurance renewals: Vehicle and other insurance premiums need to be planned before their renewal dates.
3. Festivals: Diwali, Eid and other family celebrations can involve shopping, gifts, travel and household expenses.
4. Vehicle maintenance: Regular servicing, tyre replacement and repairs can be expensive when several costs occur together.
5. Home maintenance: Painting, plumbing, appliance repairs and other maintenance expenses can be planned ahead.
Sinking Fund vs Emergency Fund: What Is the Difference?
These two savings methods serve different purposes.
| Feature | Sinking Fund | Emergency Fund |
|---|---|---|
| Purpose | Planned expenses | Unexpected financial problems |
| Examples | Insurance, school fees | Job loss, urgent medical costs |
| Saving period | Based on expense date | Built continuously |
| Withdrawal | When planned bill arrives | When a genuine emergency occurs |
| Main benefit | Better expense planning | Financial protection |
For example, an annual insurance premium is a planned expense. It should generally be covered through a sinking fund rather than an emergency fund.
An unexpected loss of income is different and may require emergency savings.
Both are useful parts of household financial planning.
How to Calculate Your Monthly Sinking Fund Contribution
Calculating a sinking fund is straightforward.
Formula:
Monthly Savings Required = Expected Expense ÷ Number of Months Remaining
Let's understand this with an example.
Suppose you want to prepare for the following annual expenses:
| Expense | Annual target |
|---|---|
| School fees | ₹30,000 |
| Vehicle insurance | ₹12,000 |
| Vehicle servicing | ₹6,000 |
| Festival expenses | ₹12,000 |
| Home maintenance | ₹12,000 |
| Total | ₹72,000 |
If you start saving 12 months before these expenses are due:
₹72,000 ÷ 12 = ₹6,000 per month.
You would need to set aside ₹6,000 every month to meet these five planned expenses.
These figures are illustrative. Your actual contribution will depend on your household expenses and payment dates.
A Practical Monthly Sinking Fund Example
Imagine a family wants to prepare for annual expenses without putting pressure on its regular monthly budget.
It can divide the savings target into separate categories.
| Savings category | Monthly contribution |
|---|---|
| Education | ₹2,500 |
| Insurance | ₹1,000 |
| Vehicle maintenance | ₹500 |
| Festivals | ₹1,000 |
| Home repairs | ₹1,000 |
| Total | ₹6,000 |
After 12 months, assuming all contributions are made and no money is withdrawn, the family will have ₹72,000 available.
Keeping separate records for each goal makes it easier to understand how much money is available for each upcoming payment.
7 Steps to Create a Sinking Fund in India
1. List Your Upcoming Annual Expenses
Start by reviewing your previous 12 months of bank statements, bills, insurance documents and school fee receipts.
Write down expenses that occur regularly but are not paid every month.
Include both fixed and estimated expenses.
2. Estimate How Much Each Expense Will Cost
Use previous bills as a starting point.
For example, if last year's vehicle servicing cost ₹5,000, you might set a slightly higher target for the next year.
Do not assume that every expense will remain unchanged.
3. Check the Payment Due Dates
The number of months available determines how much you need to save.
If a ₹12,000 payment is due in six months, your monthly contribution will be ₹2,000.
If the same payment is due in 12 months, you will need only ₹1,000 per month.
4. Divide the Target Into Monthly Contributions
Use the sinking fund formula to calculate your contribution for every goal.
If your monthly savings requirement is too high, prioritise expenses with earlier due dates and essential payments.
5. Keep the Money Separate From Daily Spending
You can use a separate savings account or a clearly organised savings balance to avoid mixing planned savings with everyday spending money.
Maintain a simple spreadsheet or notebook showing:
- Savings goal
- Target amount
- Monthly contribution
- Amount accumulated
- Payment due date
6. Automate Your Savings
Where your bank supports it, schedule a recurring transfer after your income arrives.
This makes it easier to maintain a consistent savings habit.
Make sure the transfer amount is affordable and that sufficient money remains available for essential bills.
7. Review Your Sinking Funds Regularly
Review your savings plan every three months.
Check whether:
- Your expense estimates are still realistic.
- Any payment date has changed.
- You need to increase your monthly contribution.
- A goal has already been completed.
- Any money was used for an unplanned purpose.
Adjust your targets whenever necessary.
Where Should You Keep Your Sinking Fund Money?
The right place depends on when you need the money and how easily you must access it.
For expenses due within a few months, liquidity and safety should generally take priority over chasing higher returns.
Possible options include:
Savings account: Suitable for money that needs to remain accessible for upcoming bills.
Separate bank account: Useful for keeping planned savings away from regular spending.
Short-term fixed deposit: May be considered for money that will not be required until a known future date. Check premature withdrawal conditions and applicable charges.
Recurring deposit: Can help build savings through regular instalments, but check the maturity date, withdrawal conditions and interest calculation before opening one.
Remember that market-linked investments can fluctuate in value. Money required for a near-term compulsory payment should not be exposed to unnecessary market risk.
Common Sinking Fund Mistakes to Avoid
Even a simple savings system can become ineffective if you do not follow a few basic rules.
1. Using the money for unnecessary purchases
A sinking fund should remain dedicated to its original goal.
2. Forgetting annual expenses
Review your previous year's payments so that important expenses are not missed.
3. Setting unrealistic savings targets
Choose an amount that fits your income and essential monthly commitments.
4. Mixing all savings together
Keep a clear record of the amount reserved for each goal.
5. Starting too late
If a payment is due soon, calculate the remaining amount and months carefully. Do not assume you can build the entire fund immediately.
6. Ignoring inflation and price increases
School fees, maintenance and insurance costs may increase over time. Review your targets instead of automatically repeating last year's amounts.
Sinking Fund Example: What Happens Over 12 Months?
Suppose you save ₹2,000 every month towards a planned family expense.
| Month | Total savings |
|---|---|
| Month 1 | ₹2,000 |
| Month 3 | ₹6,000 |
| Month 6 | ₹12,000 |
| Month 9 | ₹18,000 |
| Month 12 | ₹24,000 |
By consistently saving ₹2,000 every month, you accumulate ₹24,000 in one year, excluding interest.
This example demonstrates how a regular savings habit can make a future payment easier to manage.
Frequently Asked Questions
1. What is a sinking fund in simple words?
A sinking fund is money saved regularly for a specific planned expense in the future, such as school fees, insurance premiums, festivals or vehicle repairs.
2. How much should I save in a sinking fund every month?
It depends on your expected expense and the time remaining. Divide the total expected cost by the number of months available to calculate your monthly contribution.
3. Can I create multiple sinking funds?
Yes. You can maintain separate savings goals for education, insurance, vehicle maintenance, festivals, travel and home repairs.
4. Is a sinking fund better than an emergency fund?
Neither replaces the other. A sinking fund prepares you for known expenses, while an emergency fund protects you against unexpected financial difficulties.
5. Can I use a savings account for a sinking fund?
Yes. A savings account can be suitable when you need easy access to money for upcoming payments. Compare account conditions and applicable charges.
6. Should I invest my sinking fund money in mutual funds?
It depends on the time horizon and risk involved. For short-term planned expenses, protecting the required amount and maintaining liquidity are generally more important than seeking higher returns.
7. Can a sinking fund help me avoid personal loans?
It can reduce the need to borrow for expenses that are known in advance. However, it cannot eliminate borrowing needs caused by every unexpected financial situation.
Final Thoughts
Managing annual expenses does not have to become a financial emergency.
A sinking fund allows you to prepare for future payments through small, regular savings contributions. Whether you are planning school fees, insurance renewals, vehicle servicing or festival expenses, the method can make household budgeting more organised.
Start by identifying one upcoming expense, calculate the monthly amount required and begin saving consistently.
The goal is not to save a huge amount immediately. It is to make future expenses easier to manage without unnecessary financial stress.
Disclaimer: This article is for educational purposes only. It does not constitute personalised financial, investment or tax advice. Readers should review their own financial circumstances and verify relevant bank terms before making financial decisions.
Related Reading on FinanceBlogg
- How to Create a Monthly Budget in India
- Emergency Funds: How Much Should You Save?
- How to Save Money on Everyday Expenses in India
- How to Save Money on an Irregular Income in India
Suggested Sources for Further Reading
- Reserve Bank of India: https://www.rbi.org.in/ (opens in a new tab)
- DICGC: https://www.dicgc.org.in/ (opens in a new tab)
- National Savings Institute: https://www.nsiindia.gov.in/ (opens in a new tab)
About the author
FinanceBlogg Editorial Team
Editorial Team
The FinanceBlogg editorial team researches and writes educational explainers on personal finance in India. Articles are based on official sources such as the Reserve Bank of India, SEBI, IRDAI and the Income Tax Department, and are updated when rules change.
View profile and articlesSpotted an error? Read our corrections policy and tell us.
Related articles
How to Save Money on Everyday Expenses in India: 15 Practical Ways That Actually Work
Learn 15 practical ways to save money on everyday expenses in India. Reduce grocery, electricity, shopping and transportation costs with simple daily habits.
· 12 min read
How to Save Money on an Irregular Income in India: A Practical Step-by-Step Plan
Learn how to save money on an irregular income in India with a flexible budget, priority-based spending, emergency savings and a simple monthly plan.
· 9 min read
How to Create a Monthly Budget in India: A Beginner's Guide
Learn how to create a monthly budget in India, manage expenses, save money regularly and build better financial habits with a simple step-by-step guide.
· 4 min read